1 Definition of CTMC
A continuous-time Markov Chain (CTMC) is { X t , t ≥ 0 } S P ( X t n = i n | X t 1 = i 1 , ⋯ , X t n − 1 = i n − 1 ) = P ( X t n = i n | X t n − 1 = i n − 1 ) 0 ≤ t 1 < ⋯ < t n i 1 , ⋯ , i n ∈ S
Compared with DTMC where t
Similarly, it is homogeneous if P ( X t + n = j | X n = i ) = P ( X t = j | X 0 = i ) = p i j ( t ) t , u > 0 i , j ∈ S p i j ( t ) transition probability , and P ( t ) = ( p i j ( t ) ) i , j ∈ S transition probability metric .p i j ( 0 ) = δ i j P ( 0 ) = I
Claim (Chapman-Kolmogorov Equation)
For homogeneous MC, P ( t ) P ( u ) = P ( t + u ) , ∀ t , u ≥ 0.
∀ i , j ∈ S P i j ( t + u ) = P ( X t + u = j | X 0 = i ) = ∑ X ∈ S P ( X t + u = j | X u = k , X 0 = i ) ⏟ P ( X t + u = j | X u = k ) = p k j ( u ) ⋅ P ( X u = k | X 0 = i ) ⏟ p i k ( u ) .
2 Constraints on CTMC
{ P ( t ) } standard if lim h → 0 + P ( h ) = I
Claim (Continuity of CTMC)
{ P ( t ) } ⇒ p i j ( t ) t ∀ i , j ∈ S
∀ t > 0 CK Equation , | p i j ( t + h ) − p i j ( t ) | = | ∑ k ∈ S p i k ( h ) p k j ( t ) − p i j ( t ) | = | ( p i i ( h ) − 1 ) p i j ( t ) + ∑ k ≠ i p i k ( h ) p k j ( t ) | ≤ ( 1 − p i i ( h ) ) p i j ( t ) + ∑ k ≠ i p i k ( h ) = ( 1 − p i i ( h ) ) p i j ( t ) + ( 1 − p i i ( h ) ) → 0 , h → 0 + , lim n → 0 + p i i ( h ) = 0
Let { P ( t ) } ∀ i , j ∈ S rates exist:
q i = Δ lim h → 0 + 1 − p i i ( h ) h ∈ [ 0 , ∞ ] q i j = Δ lim h → 0 + p i j ( h ) h ∈ [ 0 , ∞ ]
With q i i = − q i Q = ( q i j ) i , j ∈ S generator/Q matrix of the Markov Chain.
{ X t } stable if q i < ∞ , ∀ i ∈ S { X t } conservative if q i = ∑ j ≠ i q i j , ∀ i ∈ S
We will assume standard, stable and conservative MC. Under such case, we can show p i i ( h ) = 1 − q i h + o ( h ) , p i j ( h ) = q i j h + o ( h ) .
3 Differentiation of Transition Matrix
Kolmogorov Forward Equation
d P ( t ) d t = P ( t ) Q .
Here d P ( t ) d t = lim h → 0 + P ( t + h ) − P ( h ) h
d P ( t ) d t = lim h → 0 + P ( t + h ) − P ( h ) h = lim h → 0 + P ( t ) P ( h ) − P ( t ) h = P ( t ) lim h → 0 + P ( h ) − I h = P ( t ) Q .
Similarly
Kolmogorov Backward Equation
If initial condition is P ( 0 ) = I P ( t ) = e t Q = ∑ k = 0 ∞ ( t Q ) k k ! .
Since row sums of Q KFE d P ( t ) d t ⋅ 1 → = P ( t ) Q 1 → = 0 → , P ( t ) ⋅ 1 → = C → P ( 0 ) = I C → = 1 →
Suppose X ( t ) = i ∈ S H = inf { u > 0 | X ( t + u ) ≠ i } ∼ Exp ( q i )
For a , b > 0 P ( H > a + b | H > a ) = P ( H > a + b | X ( t + a ) = i ) = P ( H > b ) , H ∼ Exp ( λ ) λ F H ( u ) = P ( H ≤ u ) = 1 − e − λ u F H ′ ( 0 ) = λ . 1 − F H ( u ) = P ( H > u ) = [ P ( u ) ] i i ⇒ F H ′ ( u ) = − [ P ′ ( u ) ] i i = − [ P ( u ) Q ] i i . P ( 0 ) = I KFE F H ′ ( 0 ) = − [ I Q ] i i = − q i i = q i .
Example 1 (Poisson Process)
{ X t } S = N Q = [ − λ λ 0 0 0 ⋯ 0 − λ λ 0 0 ⋯ 0 0 − λ λ 0 ⋯ ⋮ ⋮ ⋮ ⋱ ⋱ ⋱ ] . P ( X t = j | X 0 = 0 ) = [ P ( t ) ] 0 j KFE , P ′ ( t ) = P ( t ) Q ⇒ [ P ′ ( t ) ] 00 = [ P ( t ) ] 00 q 00 = − λ [ P ( t ) ] 00 , [ P ( 0 ) ] 00 = [ I ] 00 = 1 [ P ( t ) ] 00 = e − λ t j ≥ 1 [ P ′ ( t ) ] 0 j = [ P ( t ) ] 0 j q j j + [ P ( t ) ] 0 , j − 1 q j − 1 , j , [ P ( t ) ] 0 j = ( λ t ) j e − λ t j ! .
Example 2 (Birth Death Processes)
Q = [ − λ 0 λ 0 μ 1 − ( μ 1 + λ 1 ) λ 1 μ 2 − ( μ 2 + λ 2 ) λ 2 ⋱ ⋱ ⋱ ] .
A system of coupled ODEs from KBE: P 0 j ′ ( t ) = − λ 0 P 0 j ( t ) + λ 0 P 1 j ( t ) , P i j ′ ( t ) = μ i P i − 1 , j ( t ) − ( μ i + λ i ) P i j ( t ) + λ i P i + 1 , j ( t ) , i ≥ 1 , P i j ( 0 ) = δ i j
The closed form solutions are known for various special cases.
Otherwise the system can be solved numerically.
4 Jump Process, Jump Chain, Embedded Chain
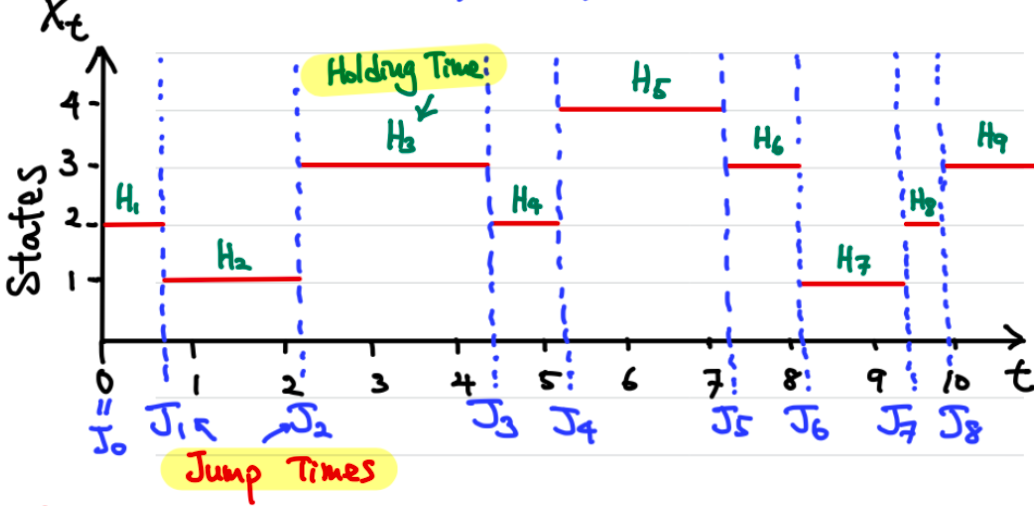
For DTMC, { Y n | n ∈ N 0 } Y n = X J n J n n
The transition matrix P ~ = ( p ~ i j ) p ~ i i = { 0 , q i i ≠ 0 , 1 , q i i = 0 , ∀ i ∈ S , p ~ i j = q i j q i = q i j − q i i , ∀ i , j ∈ S , i ≠ j . n H n ⊥ ⊥ Y n